Zelensky reveals Palisa's refusal to become ambassador to the US and names alternative candidates
Ukrainian President stated that Pavlo Palisa declined the appointment as ambassador to the US, naming other candidates considered.
Ukrainian President stated that Pavlo Palisa declined the appointment as ambassador to the US, naming other candidates considered.
Kyiv District Administrative Court opened proceedings against the city council and the Kyiv City State Administration. The plaintiff seeks to annul decisions replacing free permits with paid cards.
Ukraine's president explained why the involvement of European partners is critical for implementing state protection options and financing post-war reconstruction.
The government is considering using databases from the State Tax Service, the Pension Fund, and mobile operators to find citizens who have not registered for military service.
Ukrainian President believes fuel agreement creates preconditions for lifting restrictions against Russian individuals and compromises in energy sector.
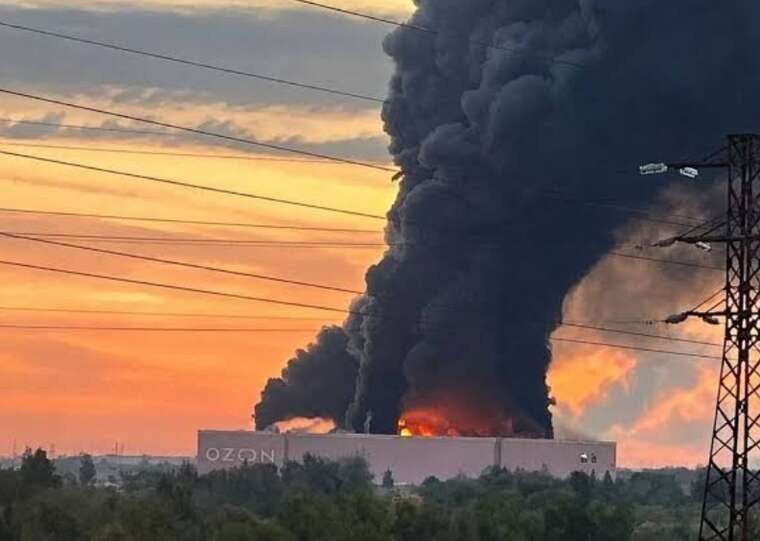
Russian e-commerce platform Ozon reported setting aside reserves of 30.1 billion rubles due to warehouse fires caused by UAV attacks in the third quarter of 2026.
Ukrainian intelligence has identified key participants in the development of a low-orbit communication system intended for the Russian military.
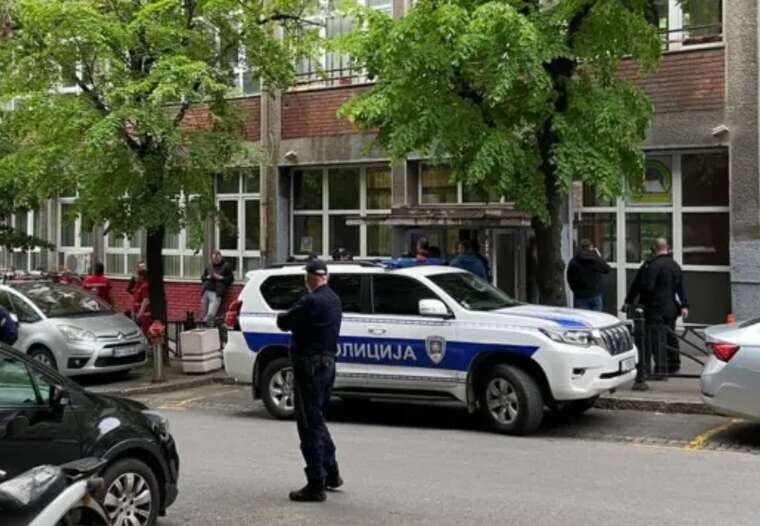
Serbian authorities introduced a red level of terrorist threat after an Israeli embassy security guard killed the minor attacker near the diplomatic mission.
The Sixth Administrative Court of Appeal has concluded its review of the case concerning the taxation of income earned by a Ukrainian creator on the OnlyFans platform. On 5 October 2026, the panel of judges issued a ruling that cancelled a significant portion of the tax liabilities imposed on the taxpayer.
According to the materials of case No. 320/46413/25, the lawsuit filed by Anna Vyacheslavivna Shilo against the capital office of the State Tax Service (STS) was upheld. The court deemed most of the additional assessments unlawful, leaving only the penalty sanction in force.
The events began after the Ukrainian tax authority received information from the competent authorities of the United Kingdom. The data was provided by Fenix International Ltd, the operator of the OnlyFans platform. According to this information, a Ukrainian user allegedly received income exceeding 109,000 US dollars from content creation during the period of 2021–2022.
The STS classified these funds as undeclared foreign income. Since annual declarations had not been submitted, tax officers assessed a total amount of nearly 970,000 hryvnia. This sum included personal income tax (PIT), the military levy, and fines.
The appellate instance established that the tax authority had acted formally, ignoring basic requirements for the evidentiary base. The court pointed to two key violations:
The court upheld the cancellation of the additional assessments for PIT, the military levy, and fines for non-declaration. The only lawful penalty recognised was a fine of 8,000 hryvnia. The court justified this by noting that the creator had failed to provide explanations in response to an official written request from tax officers at the time.
Comments
No comments yet. Be the first!