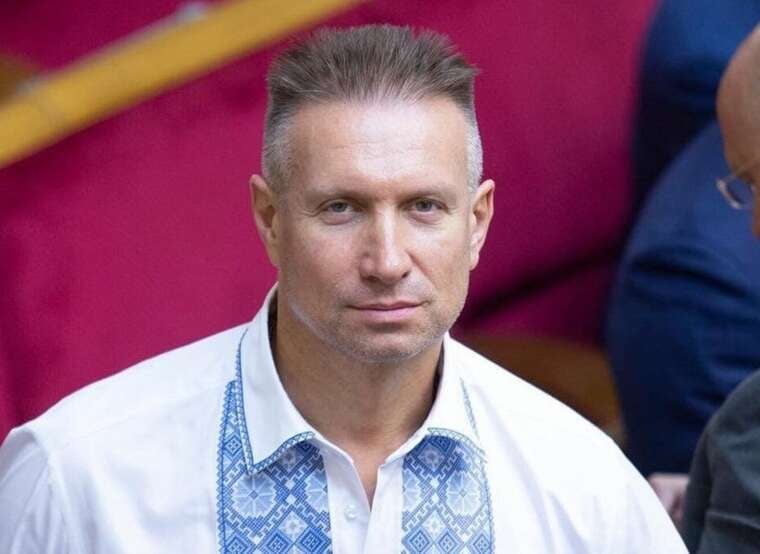
Journalists uncover hidden assets of MP Vatsak: $3.5m car fleet and state losses
Investigation reveals network of luxury cars in Gennadiy Vatsak's circle and series of violations in his business causing multi-million losses to state budget.
Investigation reveals network of luxury cars in Gennadiy Vatsak's circle and series of violations in his business causing multi-million losses to state budget.
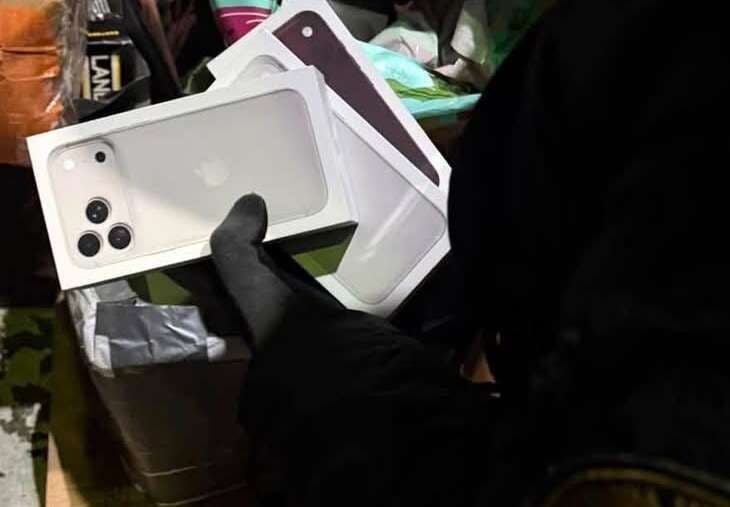
Law enforcement officers discovered a contraband batch of electronics in a minibus crossing the state border via the Krakovets – Korchova checkpoint.
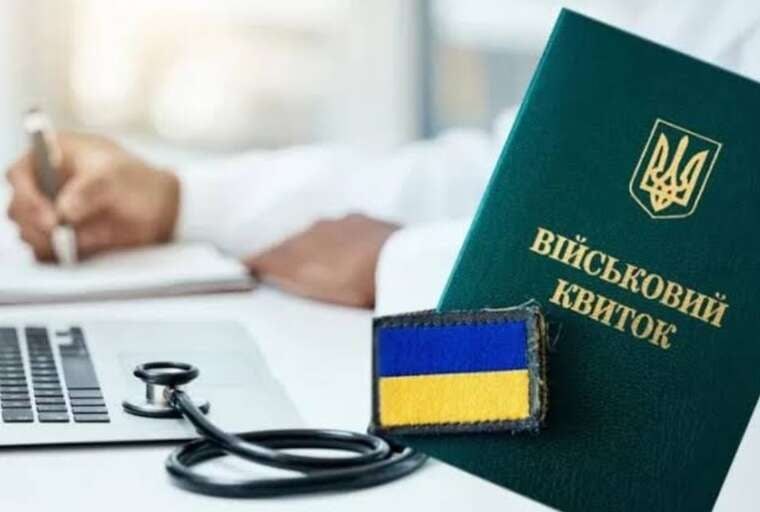
A court in Chernihiv has sentenced the head of a military medical commission to prison for establishing and leading an organised group that issued fictitious medical certificates.
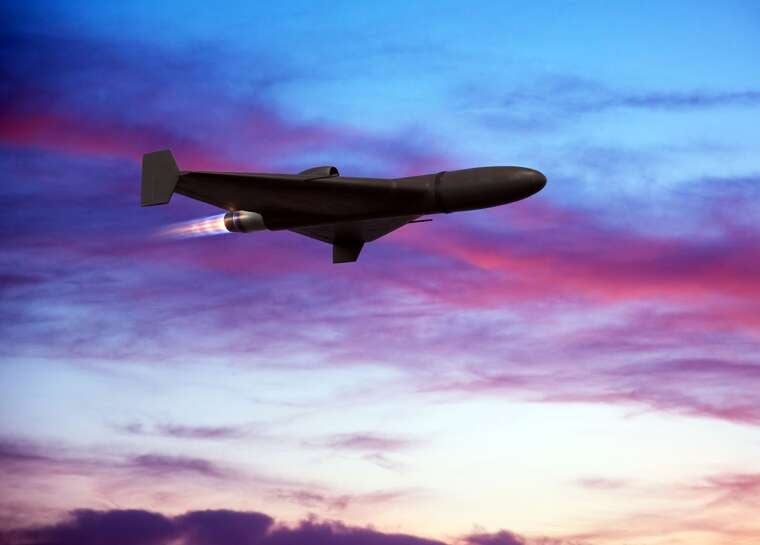
Officers Mykola Savchenko and Ihor Voloshko rescued a woman and her grandson from the rubble after a Russian shelling. During the evacuation, Savchenko lay on top of the child to protect him from a new UAV launch.
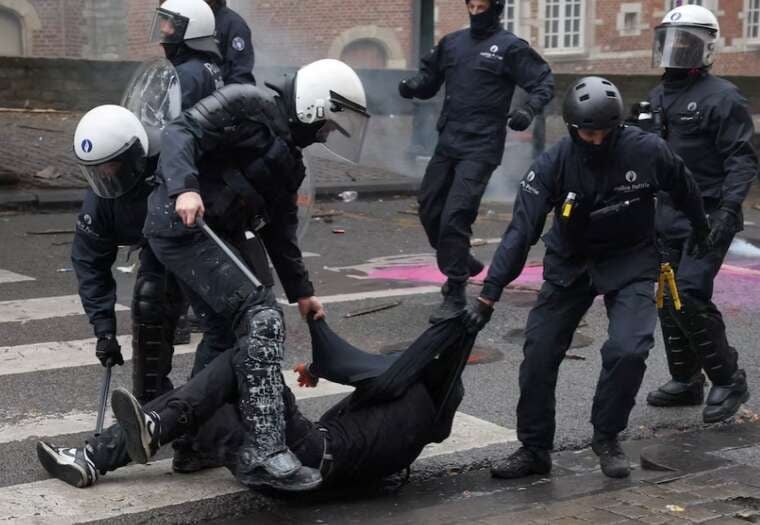
Mass march in Canada for affordable education ended in riots. Police used tear gas, and three demonstrators were detained.
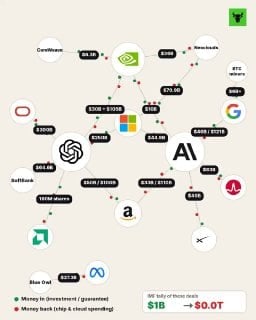
Major tech giants are financing their own clients to purchase their services. The IMF has allocated $1.4 trillion to such cyclical deals.
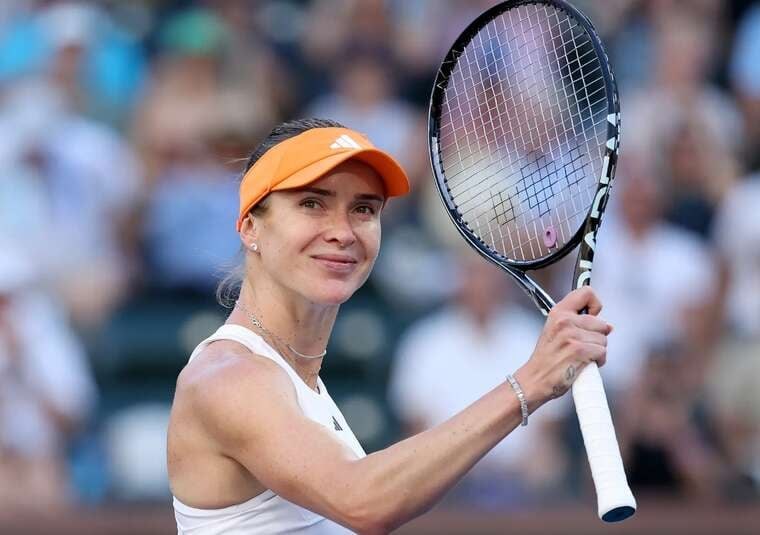
The Ukrainian tennis player secured a victory in the final round of the group stage with a score of 6:3, 3:6, 6:1 and will continue her campaign at the tournament in Indian Wells.
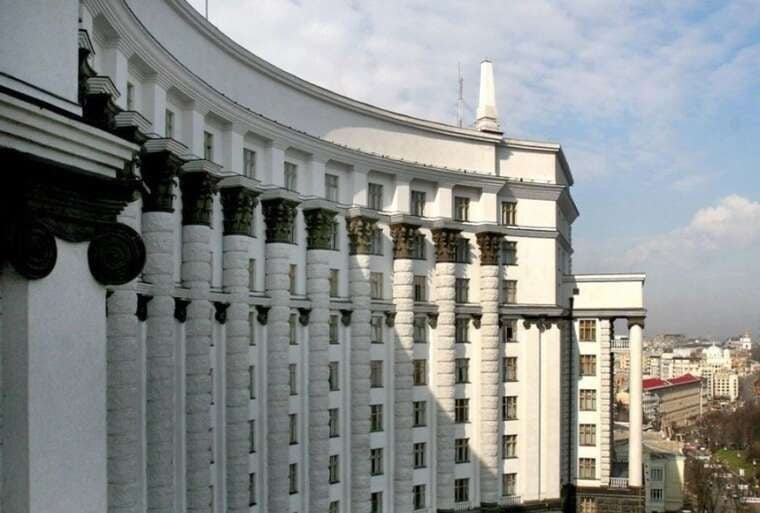
The Cabinet of Ministers approved a bill on updating the strategy, which provides for the restoration of war-damaged territories and the integration of EU requirements.
The Chernivtsi District Administrative Court concluded the review of case No. 600/2565/26-a, in which model Anastasiia Ipatii is the plaintiff. She challenged tax notification decisions issued by the Main Directorate of the State Tax Service in Chernivtsi Oblast. The court dismissed the claim, effectively confirming the legality of the back taxes amounting to over 550,000 hryvnias.
The tax service initiated the audit, conducting a documentary, unscheduled, non-visit inspection. Its purpose was to determine the timeliness and completeness of tax payments on income received by a Ukrainian resident from abroad in 2023. The basis for the audit was information transmitted by competent authorities of the United Kingdom within the framework of international exchange of tax data.
During the audit, it was established that Anastasiia Ipatii received funds through the British company Fenix International Ltd, which is the operator of the OnlyFans platform. As a result of the analysis of 50 transactions, total income of US$50,124 was recorded. In hryvnia equivalent, this amount is UAH 1,903,829.36. Meanwhile, the property status and income declaration for 2023 was not submitted, and the corresponding taxes and military levy were not paid.
As a result of the audit, the tax authority assessed the following amounts:
The court ruling noted several key points. First, the court recognised as admissible evidence obtained from foreign tax authorities on the basis of international conventions. Such data can be used for conducting audits and assessing back taxes.
Second, the court emphasised that receiving funds from content monetisation is classified as foreign income of a Ukrainian resident. Such income is subject to mandatory declaration and taxation at rates of: 18% for PIT and 1.5% for the military levy.
Third, the court found the claim unfounded, as the plaintiff failed to refute the fact of receiving funds and did not provide evidence of tax payments in the country of origin of the income.
Comments
No comments yet. Be the first!