67% of respondents unable to confidently distinguish AI-generated content from real
Joint experiment by Cosmolot and Vector reveals only a third of participants successfully identified materials generated by neural networks.
Joint experiment by Cosmolot and Vector reveals only a third of participants successfully identified materials generated by neural networks.
The cash currency market will operate with a high spread on Saturday. Experts explain why prices differ at exchange offices and how to choose a favourable offer.
A ballistic missile that failed to detonate has been found in the courtyard of a residential building in the capital's Podil district.
Banking secrecy protects transfer data, but financial monitoring can flag unusual activity. Only business income or gifts from non-relatives are taxable.
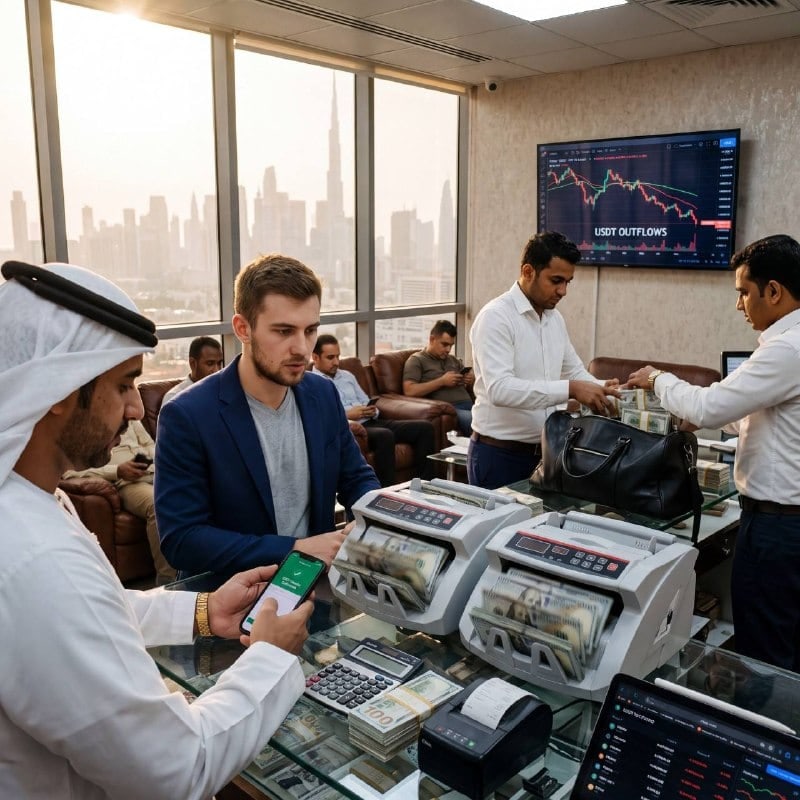
Stablecoin supply has shrunk by $16bn over the past 30 days, marking the fastest outflow of funds since 2022. Experts discuss the causes of this phenomenon and its potential implications for the crypto market.
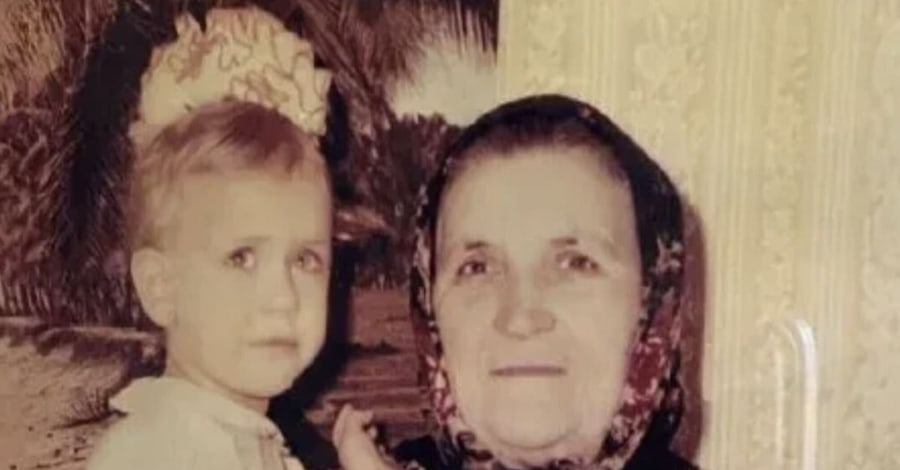
The TV presenter shared an archival photo with her grandmother and told about a strange coincidence that linked her childhood to her first major career trip.
Nikolov from the Centre for Countering Corruption commented on Kravchenko's investigation, claiming that such reports gradually undermine public trust rather than evidence specific offences.
Expert Serhiy Kuyun forecasts further cheapening of fuel at gas stations over the coming weeks. The main factor is the sharp drop in global oil prices and market normalisation.
Transferring funds between bank cards has become a standard tool for settling bills for shared meals, repaying debts, or providing financial support to relatives. The mere crediting of money to an account does not automatically trigger a notification to tax authorities or create an obligation to pay tax.
Under Article 60 of the Law of Ukraine "On Banks and Banking Activity," information about clients' accounts and transactions is protected by banking secrecy. The State Tax Administration does not have free access to citizens' statements and does not receive automatic notifications about every transfer between individuals.
However, legislation defines a clear procedure for disclosing such data. According to Article 62 of the same law, the tax authority may, upon request, determine whether specific accounts or e-wallets are opened to a particular person. However, obtaining detailed information about fund movements, balances, or transaction volumes requires a court decision.
It is important to distinguish between tax control and bank financial monitoring. Banking institutions are obliged to analyse clients' transactions and respond to suspicious activity. If a payment raises questions, the bank has the right to suspend it and request documents confirming the legal origin of the funds. In the absence of convincing explanations or as required by law, the materials are forwarded to the State Financial Monitoring Service.
Mandatory financial monitoring applies to transactions of 400,000 hryvnia or more. However, checks can also be initiated for smaller amounts if the transactions appear unusual. Regulators may pay attention to the following signs:
A bank's request regarding the origin of funds is not in itself a sign of a tax law violation. The main goal of financial monitoring is to verify the legality of the source of funds, not to assess taxes.
A tax obligation arises not from the fact of money being credited, but depending on the basis of the payment. The following, in particular, are not considered taxable income:
Special rules apply to cash gifts, established by Article 174 of the Tax Code of Ukraine. No tax is payable if the gift comes from a first- or second-degree relative: parents, husband or wife, children, full brothers and sisters, grandparents, or grandchildren. If, however, the money was gifted by another citizen of Ukraine, the recipient is obliged to pay 5% personal income tax and 5% military levy.
If a card receives payment for sold goods, provided services, or property rental, these funds may be considered income. A person receiving such earnings without registering business activity must pay taxes on general grounds: 18% personal income tax and 5% military levy. These incomes must be declared in the annual declaration of property status and income. The document is submitted by 1 May of the year following the reporting year, and taxes are paid by 1 August.
Systematic payment for goods or services to a personal card may indicate the conduct of business activity, which is prohibited without proper registration. For such a violation, Article 164 of the Code of Ukraine on Administrative Offences provides for a fine of 17,000 to 34,000 hryvnia. The court also has the right to confiscate the produced goods, production tools, and funds obtained as a result of unregistered activity.
If a bank or tax authority requires an explanation of the origin of funds, relevant documents will help. These include written IOUs for the provision and repayment of loans, gift, lease, or property sale and purchase agreements, as well as checks and receipts confirming joint expenses. It is also advisable to specify in the payment purpose that the funds are a debt repayment or support for relatives.
«Найкраще рішення для тих, хто веде власну справу, завести окремий банківський рахунок під бізнес, а особисту картку залишити виключно для побутових потреб» ("The best solution for those who run their own business is to open a separate bank account for the business and keep the personal card exclusively for household needs").
Separating personal and commercial funds allows one not to mix payments for goods or services with private transfers. For business activity, it is advisable to use a separate bank account, while the personal card should be used for everyday needs.
Comments
No comments yet. Be the first!